What a home really costs each month, and why first-time buyers have more say in it than they think.
Most first-time buyers we sit down with start the same way. They have seen a price on a listing, heard a rate on the news, done some quick math in their head, and decided the answer is no before we have even said hello.
We get it. Both numbers feel big right now. But after years of helping people buy homes at the Jersey Shore, here is what we have learned: nobody lives in a price. You live in a payment. And a payment has more moving parts than a price tag or an interest rate, which means you have more say in it than you think.
What a Rate Really Does to Your Monthly Payment
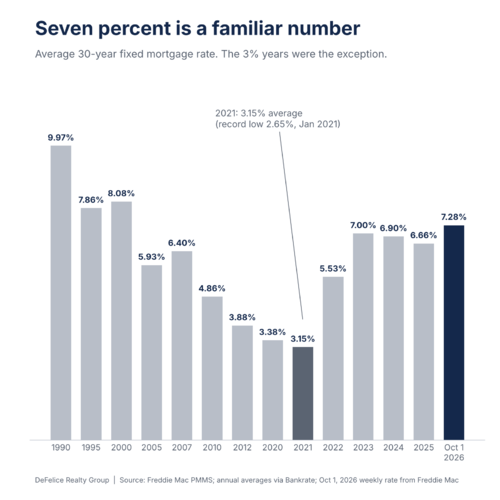
Let’s put real numbers on it. Take a $400,000 loan on a 30 year fixed. At 6 percent, principal and interest comes to about $2,398 a month. At 6.5 percent, about $2,528. At 7 percent, about $2,661. That is an example, not a quote, and it leaves out taxes and insurance. But look at the gap. Half a point of rate is roughly $130 a month. That is real money and we never wave it away. It is also a number you can plan around, not a wall.
The Other Dials You Can Turn
Now look at the other dials, because there are several. Every $10,000 you negotiate off the price takes roughly $63 a month off that same 6.5 percent payment. A seller who has been sitting on a house for a few weeks may be happy to talk about price, or about helping with closing costs, or about paying for a rate buydown that lowers your payment for the first years of the loan or for the life of it. It depends on the house and the seller, but it is worth asking, and we ask for our buyers.
The loan itself matters too. Not everyone needs 20 percent down. FHA and conventional loans can go much lower, and New Jersey has first-time buyer programs through NJHMFA that may help with down payment and closing costs. Terms and eligibility change, so we check what is current before we promise anything. Then there is the lender. Two lenders can look at the same buyer and come back with different rates and different fees. Getting more than one quote is not rude. It is smart, and good lenders expect it.
Don’t Forget Taxes and Insurance
Do not skip the part of the payment people forget: property taxes and insurance. In New Jersey, two homes with the same price can carry very different tax bills depending on the town. A house two towns over, listed at the exact same price, can come with a lower tax bill and a lower monthly payment. We have seen buyers realize that after falling for the first house, and it changed where they looked. Always compare the whole payment, not just the list price.
Your Starting Rate Is Not Forever
And if you buy and rates come down later, you can look at refinancing. We cannot promise where rates are headed, and a refinance has its own costs, so we would never tell you to count on it. But the rate you start with does not have to be the rate you keep forever.
Pick a Payment You Can Live With
Here is the part we most want you to hear. The right payment is the one that lets you buy the home and still enjoy your life in it. Dinner out, a vacation, a cushion for the water heater that decides to quit. We would rather help you land comfortably in a home than stretch to the edge of what a lender will approve. You get to set that number, and we will build the plan around it.
Let’s Run Your Numbers
If you have been telling yourself it is not the right time, or that it is out of reach, come talk with us before you decide. Bring the house you have been eyeing, or just your questions. We will run the real payment together, with your numbers, and you will know exactly where you stand. No pressure and no pitch. Just a clear picture.
Reach out to the team at DeFelice Realty Group, 870 Mantoloking Rd, Brick, NJ, or call 732-920-0900, and we’ll set up a time to talk.
Rates, programs and terms change. Figures above are illustrations, not loan quotes.
Check out this article next